Renewals run on red lines
The London market’s renewal quality control is a tracked change, not a full review. Red lines and flags need owners, approvals and retained evidence — not memory.
What it is
Last Tuesday, at the LMA's Dispelling the Myths and Misunderstandings of Insurance Law panel, a barrister said out loud the thing every London market practitioner has always known but nobody says in a room with lawyers. Quoting evidence given by underwriters in previous litigation, Harry Wright of 7KBW put it this way: on a renewal, underwriters do not turn every page and read every clause, because if they did, Lloyd's would grind to a halt and no other business would ever be underwritten.
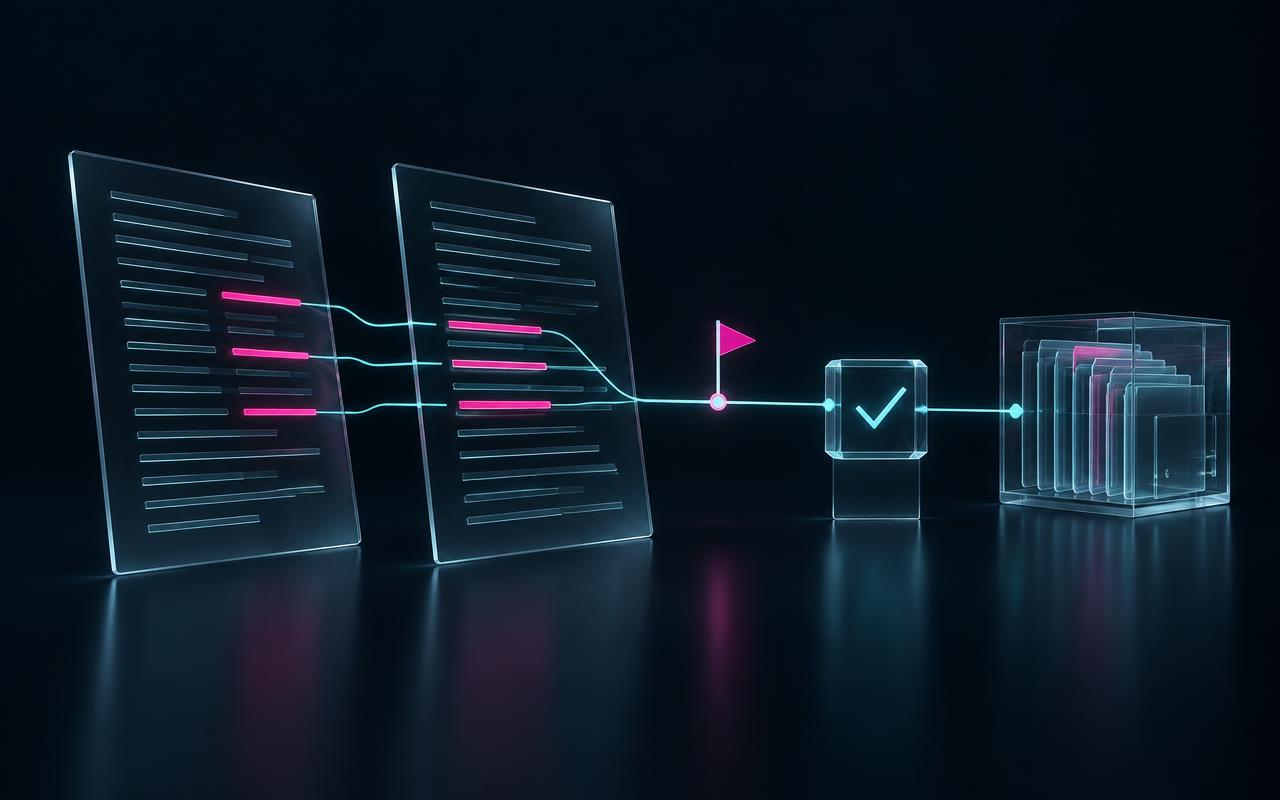
What stands in for the reading, the panel went on, is the tracked change. The market's renewal quality control is a document comparison, not a document review. The broker produces the marked-up wording, the underwriter checks the diff, the change is either flagged or it is not. Around that mechanism sits a body of hard-won practical rules: a few words can reverse a clause's meaning, particularly in exclusions, as the LMA's Arabella Ramage noted; disputes become fact-sensitive where changes were not clearly highlighted; and brokers are "very well advised" to draw amendments to underwriters' attention rather than assume they will be spotted.
Read as process, that is the market's actual verification architecture: compare, flag, sign. The contract's meaning is carried by the red lines and the courtesy that draws attention to them. Where neither exists, the meaning is carried by memory, and memory is not a legal instrument.
Why it matters now
Because the market is amending its standard forms faster than ever, and the amendment is the contract. The LMA published 50 new model wordings in 2026 alone, on war clauses, AI definitions, data centre aggregation, energy wordings, with the wordings committees still drafting. Every change to a standard clause creates a difference to be tracked, understood, and communicated, and the volume of differences is rising exactly as the people who could read a contract in their sleep are retiring.
Three forces are converging on the same thin mechanism. First, the wording book is getting more complicated: the market's response to war risk, to AI, to the data centre build-out is being written into clauses, and every clause carries its own amendment history. Second, the human layer is thinning: the claims and underwriting veterans who held the wording knowledge are leaving, and the industry's own conferences now debate how to replace judgement that was never written down. Third, the checking regime around it is shifting: the regulators' SM&CR proposals would remove the annual certificate machinery and replace it with a supervisor that reads the data, which means the evidence a firm can produce about its own operations, including its renewal process, becomes the whole of its accountability.
In that world, the red line is no longer a drafting convenience. It is the firm's record of what changed, who approved it, and who was told. When a wording dispute lands, and they do, the firm that can produce that record wins the factual argument before it starts. The firm that cannot is arguing from recollection against a document.
What firms should do
Make amendment tracking a system, not a habit.
Every renewal should generate a comparison as a matter of course, with each change logged against its owner, its approver, and the date it was accepted. That is not a document management task; it is the firm's evidence of consent. The test is simple: if a clause were litigated next year, could the firm reconstruct, from its records alone, who changed what and who agreed?
Formalise the broker's flag.
The panel was clear that brokers should draw amendments to underwriters' attention, and clear that assuming it happens is a risk. The firms that build an explicit signalling step into their renewal process, a written flag on material amendments, rather than relying on a broker's diligence, are the ones whose underwriters actually see the change that matters.
Decide, in writing, what gets read.
No firm can read every clause, but every firm can define its review standard: which clauses get a full read, which get a diff, who signs off the comparison. The alternative, which the litigation evidence describes, is a standard that nobody chose and nobody can defend.
Keep the evidence past the renewal.
The market's dispute pattern is that the wording question surfaces years after the bind. A comparison that lives only until the slip is signed is no evidence at all. The firms whose amendment records survive the renewal are the ones whose answers survive the dispute.
The opmodal perspective
This is exactly what the Architecture Canvas exists to expose: where in a process the evidence actually lives. Map the renewal chain, broker draft, tracked changes, underwriter review, sign-off, policy issuance, and mark on each node what is verified and what is assumed. The canvas makes the uncomfortable truth visible: in most firms the verification step is the one with no owner, no record, and no standard.
The comparison itself is the natural candidate for technology. Compare States, the mechanism opmodal builds into its platform, does for operating models what tracked changes did for wordings: it renders the difference between two versions as a visible, reviewable, sign-off-able artefact. Applied to renewals, it turns the broker's courtesy into a firm's record. The change is logged, the approval is owned, the evidence is kept. The firm's renewal process stops depending on one careful underwriter and starts depending on its own machinery, which is the whole point of an operating model.
The market has always known that its core asset is the underwriting decision, owned and evidenced. What last Tuesday's panel added is that the evidence is smaller than anyone admitted: a red line and a flag. The firms that systematise those two things will sail through the disputes, the retirements and the regulator's new data-driven gaze. The firms that keep relying on memory will find out, on the day it matters, that memory does not compile.
A contract is only as strong as the record of what was agreed. This week the market's own barristers said so, in public. The question for 2027 is not whether anyone reads the whole policy. It is who can prove what changed, and who agreed to it.