7 December is the first exam for Europe's T+1 operating models
The 7 December 2026 deadline is the first hard test of Europe's T+1 operating models — and the least modernised step goes first.
See also: Target State – Issue 5
It is 07:45 on a Monday morning in December. A fund you manage bought UK equities on Friday. The allocation went out late, the confirmation has not matched, and sterling has not arrived in the right account. Under the old timetable, this was a problem for later. Under the new one, the settlement instruction needed to be in the system hours ago, and the penalty clock has already started.
That Monday is 7 December 2026. It is not the T+1 go-live date. It is the first hard deadline on the way there, and it tests the least modernised step in the whole chain. This piece explains what the deadline actually requires, why it is scheduled first, and what operations teams should be doing about it this quarter.
What it is
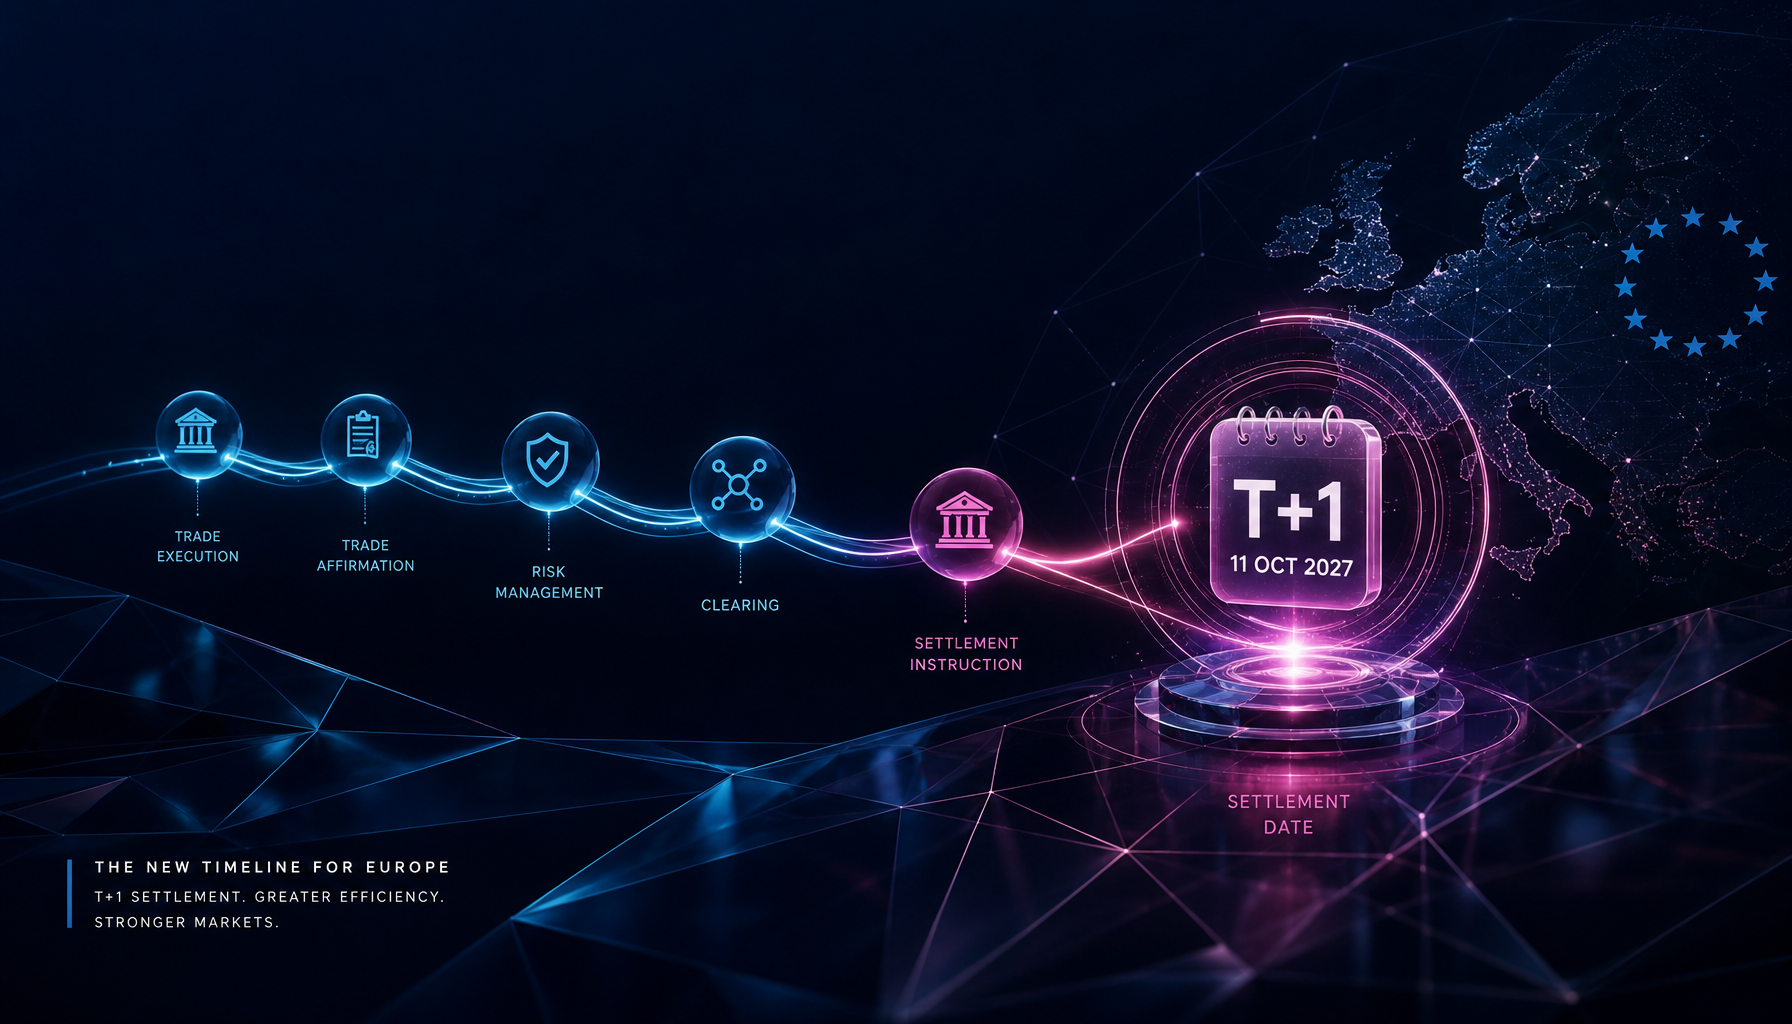
On 20 July 2026, ESMA published its statement on T+1 preparations. The structure is simple. The EU, UK and Switzerland all move to T+1 on Monday 11 October 2027. But compliance arrives in two waves.
The first wave lands on 7 December 2026 and covers the exchange of allocations and confirmations: earlier deadlines, electronic delivery, and international communication standards as the default. The second wave, the settlement layer itself, arrives with go-live in October 2027, including earlier instruction cut-offs, auto-partial settlement, hold-and-release and auto-collateralisation at CSDs.
The statement is unusually blunt about the fact that none of this should be news. The legal framework has been known since mid-October last year. ESMA's concern, after two industry readiness surveys, is not awareness but implementation, which it describes as uneven across the EU financial markets, sectors and firms. The deadline is the regulator's way of saying: the first step of the chain is the one that needs the most work, so it goes first.
Why it matters now
Allocations and confirmations are the least glamorous, most fragmented step in the settlement chain. The trade happens on one system, the allocation flows through another, the confirmation comes back from a counterparty on a third, and the instruction only lands at the CSD when all of them agree. In most firms, this is where the manual work lives: the exception queues, the rebooked tickets, the phone call to the broker's operations desk.
It is also the step where the time disappears first under T+1. The trade date is the only day you have. If the allocation is late, the confirmation cannot match. If the confirmation has not matched, the instruction is not final. If the instruction is not final, funding cannot be arranged, and the FX trade that turns euros into sterling cannot be instructed in time. One late step cascades into everything downstream, and the European Commission's settlement discipline regime already prices those failures in cash.
The industry's infrastructure is moving in response, and that is the other reason this matters now. In the past month alone, Euroclear and HSBC announced AutoFX, an automated foreign exchange service tied directly to settlement, and Citi launched Custody+, processing over 80% of its event volume in real time. The servicing layer is industrialising speed. What it cannot industrialise is your allocation and confirmation step. That remains yours, and December tests it first.
ESMA's other warning deserves to be pinned to the wall: No one can be ready in isolation. Your readiness is bounded by the counterparties around you. If your administrator still sends confirmations as PDFs, your electronic workflow stops at their doorstep. If your broker cannot match your allocation format, you inherit their failure.
What firms should do
Four things, in order.
Timestamp the chain
Map trade to allocation to confirmation to instruction to funding to settlement with actual clock times, not target times. Most firms discover the day is spent where nobody was looking: a queue between two systems, a funding sign-off that waits for a person who works different hours.
Fix the reference data first
ESMA names it explicitly: PSET, PSAF, transaction type, place of trading, standard settlement instructions. Every late allocation has a data problem underneath it. Standard settlement instructions are the cheapest win available: a clean SSI removes the most common matching failure before it happens.
Automate the step, with real counterparties
Electronic and standardised allocation and confirmation is a network problem, not a software problem. You cannot comply on your own, so do not build on your own. Test with your brokers, custodians and administrators now, in production-like conditions, while there is still time to fix what breaks.
Design for exceptions
Under T+2, the buffer absorbed the failures. Under T+1 there is no buffer. The processes that survive are exception-driven: everything that flows needs no attention, everything that breaks is visible, owned and resolved within the trade date. This is an operating model change, not a systems upgrade.
The opmodal perspective
The Architecture Canvas methodology asks one question of every process: what is the design-speed assumption underneath it? Most operating models in asset management were designed at batch speed, sized around buffers that the new settlement cycle simply removes. The 7 December deadline is the first moment those assumptions get tested against the clock, in the most fragmented step of the chain, where the hand-offs between firms are the process.
The firms that treat December as a data and workflow problem inside the allocation step will scrape through. The firms that treat it as the first repayment on a redesign, mapping the whole chain, owning every hand-off, and rebuilding around exceptions rather than buffers, will arrive at October 2027 with an operating model that is faster than the regulation requires. The deadline is not the destination. It is the first exam.