When war risk stops being a wording problem
The Gulf conflict has moved war risk beyond clause language. The firms that can aggregate exposure across classes in hours are the ones built for the new era.
What it is
For a century, war risk in the London Market has been a wording discipline. The policy language, the exclusions, the notice of cancellation clauses, the Joint War Committee circulars that redraw the map of dangerous waters. Master those documents and you understood your exposure, or so the logic went, because your exposure was defined by what the words covered.
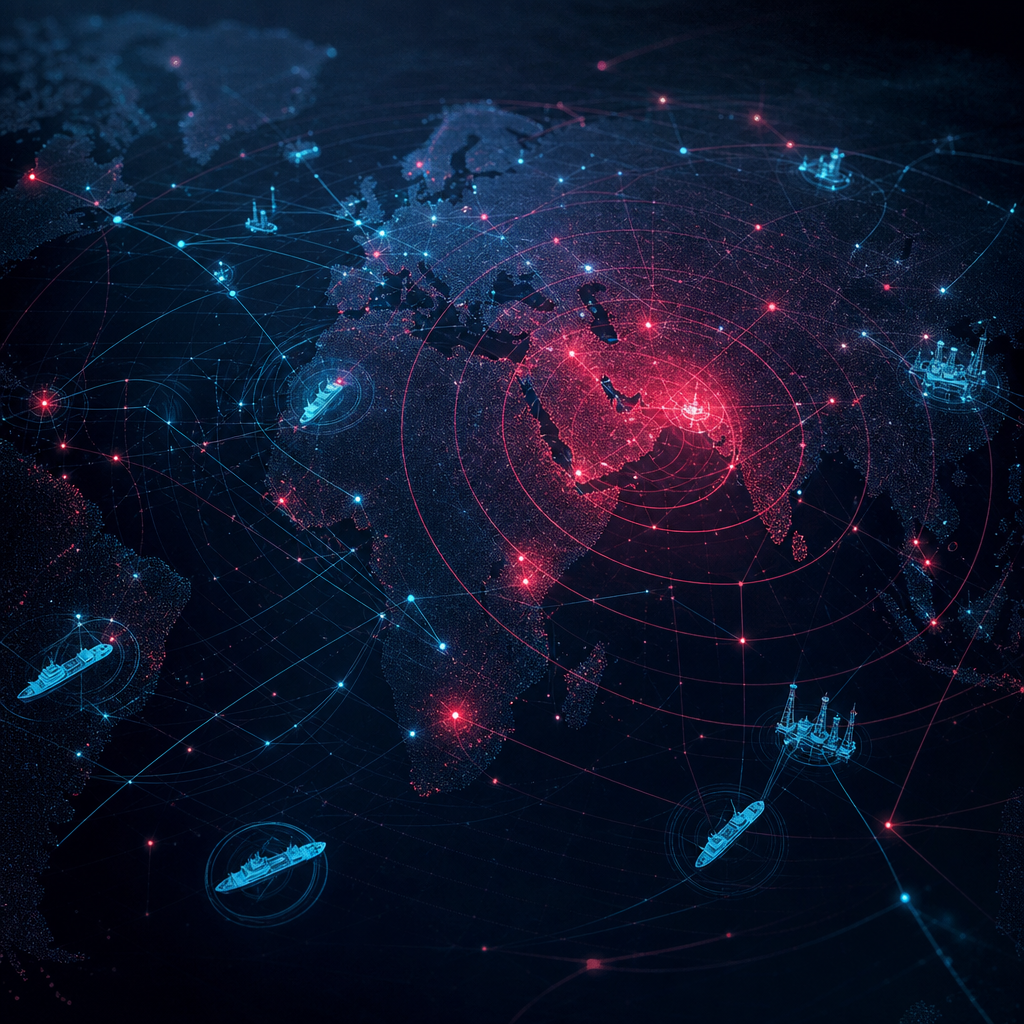
The Gulf conflict has broken that logic. The Financial Times reported last week that the market faces an estimated £1.4bn of losses from the war, and the striking detail is where the losses sit: most of them from damage to land-based infrastructure rather than the ships the war risk machinery was built around. Lloyd's own assessment, reported at $1.9bn, is that the conflict will continue and further claims will come.
Read that carefully. A war that began as a shipping crisis is now generating losses in property, energy and political violence books. The exposure did not move through the war risk clauses. It moved through ordinary commercial policies held by companies whose assets happened to be in the region. War risk has stopped being a wording problem and become an exposure management problem.
Why it matters now
The market's machinery for handling this is honest about the challenge. Lloyd's has launched a marine war risk consortium to keep Strait of Hormuz shipping insurable. Reinsurers have withdrawn war risk capacity in waves. The Joint War Committee has redrawn high-risk zones. Notice of cancellation processes, sanctions screening, aggregation reviews – the clause machinery has been running at full speed for months, and it matters, because when a vessel is hit the market needs to know who holds what.
But that machinery has a boundary, and the £1.4bn is what happens beyond it. Land-based infrastructure losses do not arrive via a war risk endorsement that someone logged in a structured field. They arrive as ordinary property damage claims, energy business interruption, political violence losses – each landing in a different class team, a different system, a different reserving view. The market-level loss estimate that Lloyd's publishes is, in effect, an aggregation exercise run across dozens of managing agents in days. It is only possible because the Corporation asks, and the market scrambles to answer.
Here is the uncomfortable question that follows. If Lloyd's can assemble a market-wide number in a week, how long does it take an individual managing agent to assemble its own? For a firm whose Gulf exposure is scattered across marine hull, cargo, war, energy, property, contingency and political violence books – each with different exposure capture, different policy systems, different reinsurance protections – the honest answer is often measured in days of spreadsheet archaeology, not hours of querying. And that answer is itself a risk statement, because the next escalation does not ask politely.
What firms should do
Three disciplines separate the firms that could answer the Gulf exposure question in an hour from the ones that could not.
Map exposure by geography and peril, not by class
War and political violence do not respect the boundaries between marine, property and energy books. The question "what do we have in the Gulf?" has to be answerable across the whole portfolio, which means exposure data captured consistently enough to aggregate across classes, territories and legal entities without a reconciliation exercise.
Treat clause changes as data events, not document events
Every Joint War Committee circular, every notice of cancellation, every widened exclusion is a change to the firm's exposure position. In most firms those changes live in the legal and compliance workflow and never touch the exposure systems. A firm whose clause lifecycle is connected to its exposure data can see the moment a circular changes its aggregate position; everyone else finds out at renewal, or at claim.
Make the aggregation chain a designed process
The Corporation's estimate works because someone owns the aggregation process end to end: who asks, who answers, what data feeds it, what controls check it, who signs the number. Syndicates should run the same process internally as a standing capability, not a scramble triggered by headlines. If the market has to answer the same question again next month – and Lloyd's assessment suggests it will – the firms that invested in the process this month will answer in hours, and the market will notice.
The opmodal perspective
We have argued for years that an organisation's exposure picture is only as good as the operating model underneath it. War risk is the purest demonstration of that principle in the market today, because it has moved from a domain where the words defined the risk to one where the geography does, and most firms' operating models are still built around the old definition.
The wording era produced a particular architecture: class-aligned books, legal-owned clause management, exposure capture optimised for pricing rather than aggregation. The infrastructure-loss era demands a different one: exposure captured at the asset and location level, aggregated across classes by geography, with the clause machinery feeding the data layer rather than sitting beside it in a document store.
This is not a hypothetical. The firms that answered Lloyd's aggregation call this month in hours rather than days now know their own position with precision. The firms that could not have discovered a gap in their operating model at the worst possible moment – during a live loss event, under the Corporation's gaze, at the exact point in the cycle when the PRA is asking about optimism gaps and the SBF is on the table.
War risk used to be a test of your wordings. It is now a test of your operating model. The market's £1.4bn bill is the clearest evidence yet of which one matters.